The CSV uploaded without a single error. Every row imported. The client’s Xero bank account showed three months of transactions, neatly timestamped, amounts intact. And one entire statement page was missing.
Nobody caught it until reconciliation, when the closing balance refused to tie. The conversion tool had processed the PDF, produced a clean file, and quietly skipped page four of a six-page statement. Xero accepted everything it received. It had no way of knowing what it never got.
That gap between “Xero accepted the file” and “the data is actually right” is where most of the real risk lives in bank statement conversion for Xero. Competitors spend thousands of words on CSV column layouts and UTF-8 encoding. Those things matter. But they’re Layer 1 of a problem that has four layers, and most accounting firms get burned on Layers 2 through 4.
By the end of this piece, you’ll have a framework for deciding whether converted bank-statement data is genuinely ready to import, not just formatted correctly.
The short version
A file that imports cleanly into Xero is not the same as a file that is correct. Import compatibility is only Layer 1 of bank statement conversion. The real workflow runs source to conversion to validation to accounting preparation to review to import to reconciliation.
- Xero accepting a file proves the format, not the accuracy.
- Verify completeness (every page, every transaction), not just the closing balance.
- A statement can balance and still be missing transactions.
- Check the client, account, period, dates, signs, and duplicates before you upload.
- Categorization and reconciliation are separate stages that come after import.
Who this applies to (and who should stop reading)
This is for accounting firms, bookkeepers, and outsourced finance teams importing bank-statement data into Xero manually. You’re doing catch-up bookkeeping, filling historical gaps, onboarding clients whose banks don’t support automatic feeds, or processing PDF statements a client handed you.
If your bank feed covers everything and you’ve never needed a manual import, this won’t be relevant. If you’re looking for a step-by-step CSV formatting tutorial, Xero Central’s manual import documentation covers the mechanics directly.
What bank statement conversion for Xero actually means
Bank statement conversion is the process of turning transaction data from a source format (usually a PDF, sometimes a proprietary bank export) into something Xero can ingest. That could be CSV, OFX, QFX, or another supported format.
The conversion itself involves extracting transaction lines, normalizing dates and amounts, structuring columns, and producing a file. What it doesn’t automatically involve is verifying that the output is complete, correctly signed, or mapped to the right client account. That’s a separate discipline, and conflating the two is where firms run into trouble.
It helps to separate the stages rather than treat conversion as the whole job:
| Stage | What happens |
|---|---|
| Conversion | Source statement becomes structured transaction data |
| Validation | Data is checked against the source |
| Preparation | Data is mapped to the required accounting structure |
| Import | Data enters the Xero bank account |
| Reconciliation | Imported transactions are matched and reconciled in Xero |
Worth noting: if the bank already provides OFX or another structured export, conversion from PDF may be unnecessary. Xero’s own documentation recommends OFX where available. The full workflow between a PDF and your accounting software involves more steps than most people assume.
Do not let the sequence collapse into “PDF to CSV to Xero equals finished bookkeeping.” It is not. Conversion is the first step, not the last.
When would an accounting firm need to convert bank statements for Xero?
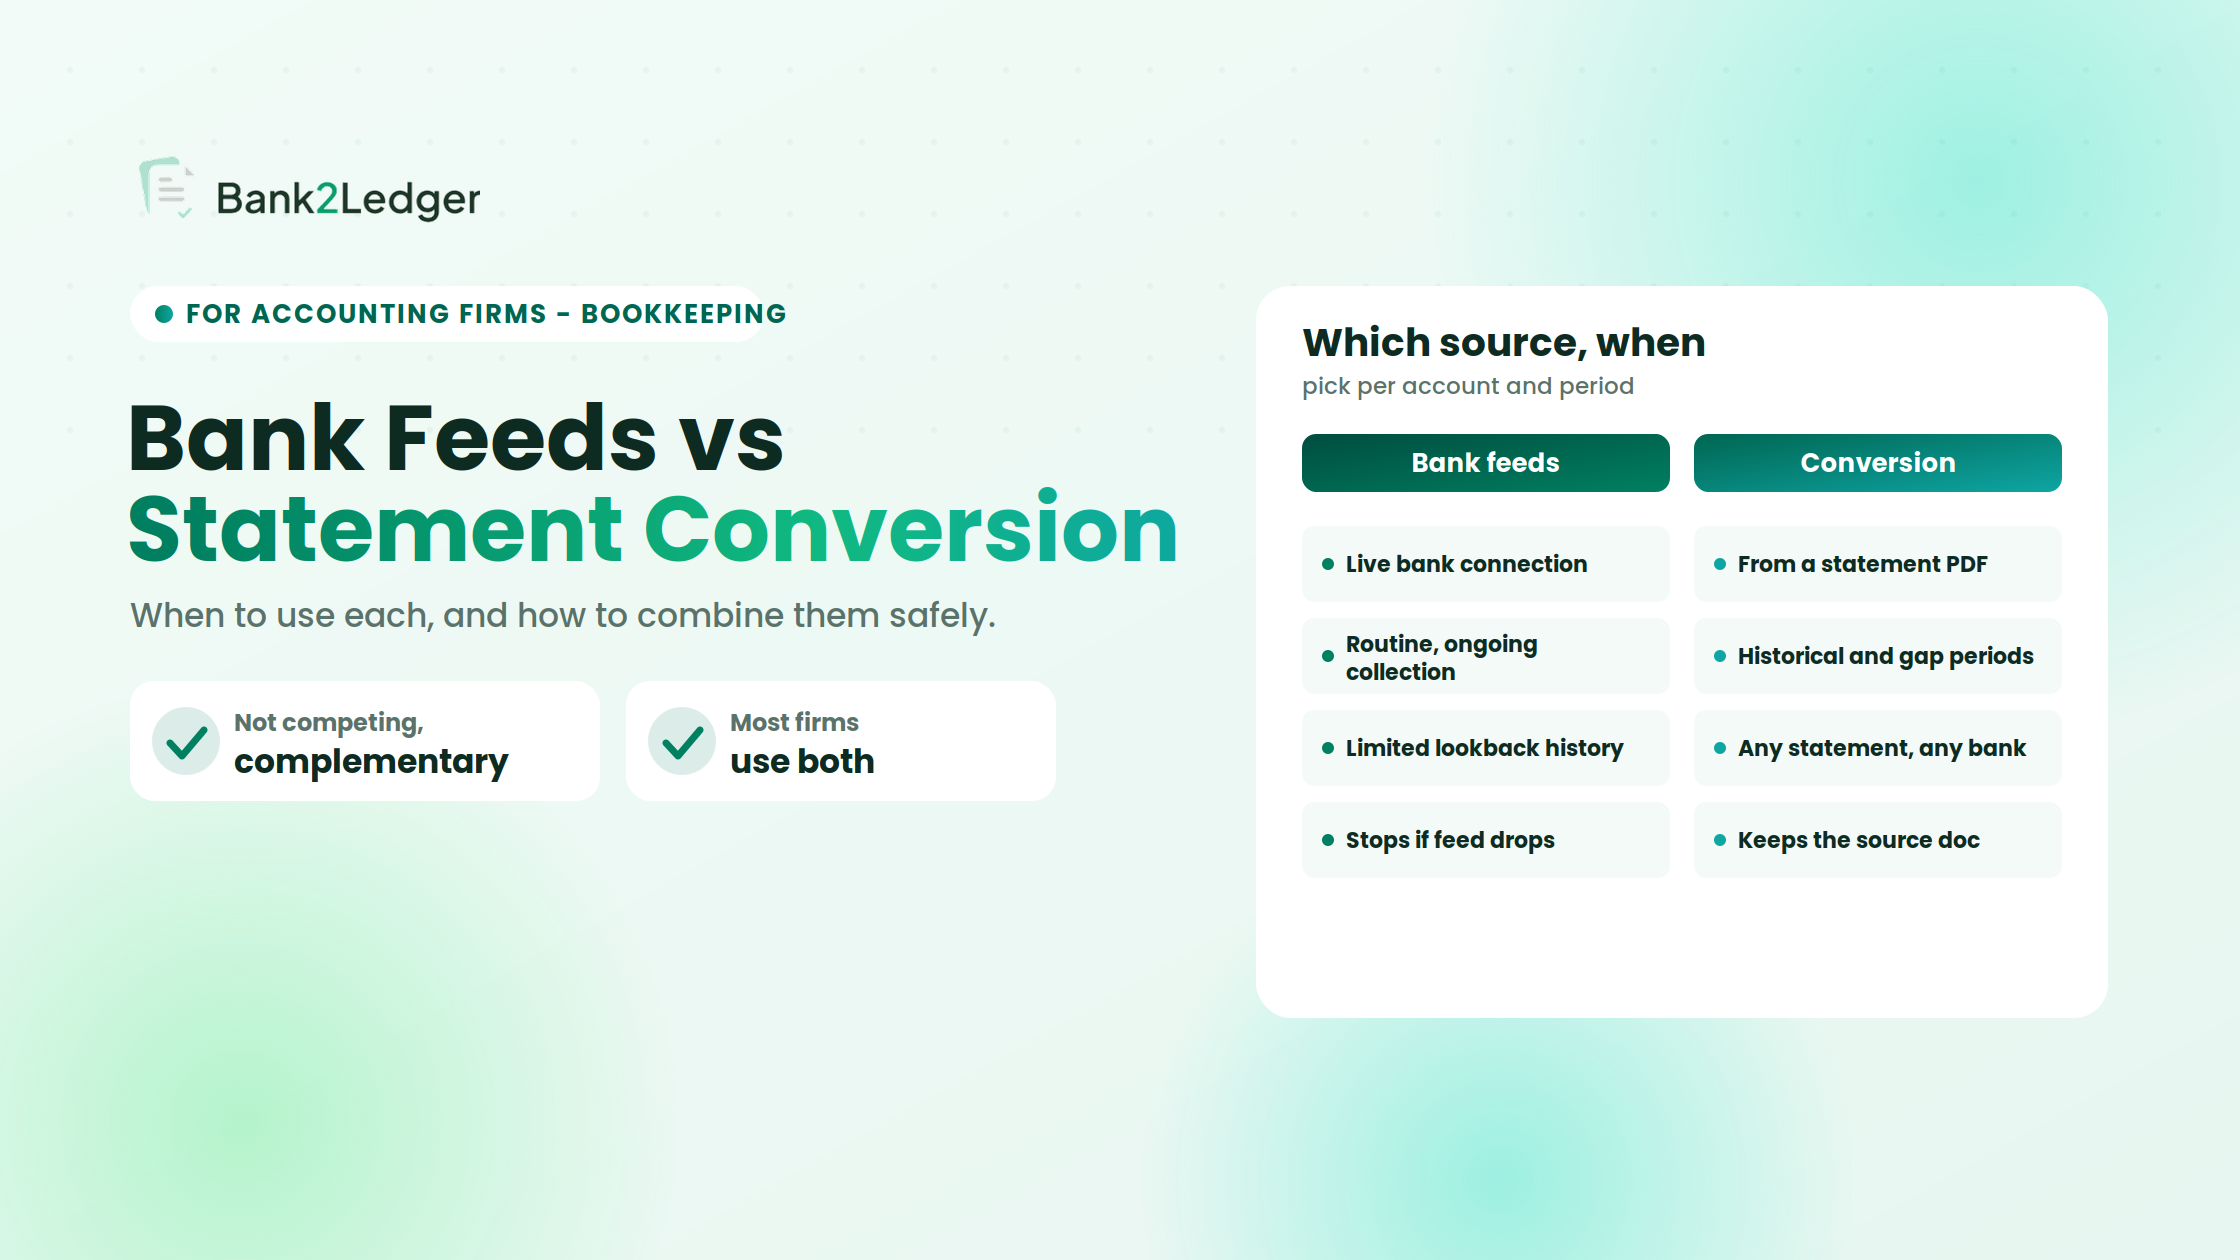
Several scenarios come up repeatedly. Each one is a reason a bank feed alone will not cover the period you need.
What file formats can Xero import?
According to Xero Central’s current documentation, manually imported formats include CSV, OFX, QFX, QIF, and QuickBooks-compatible files. PDF statement import exists but is limited to supported banks and regions. Don’t assume PDF import is available for your client’s bank without checking.
| Format | Typical use |
|---|---|
| OFX | Structured bank transaction import (recommended where available) |
| QFX | Financial-data exchange |
| QIF | Bank transaction import |
| CSV | Flexible manual import |
| QuickBooks format | Supported bank-statement import |
| Specific Xero regions, banks, and workflows only |
Xero’s supported import options can vary by region and workflow. Verify the applicable Xero documentation for the client’s organization before treating PDF import as a universal feature. Do not claim, as an absolute, that every Xero organization can (or cannot) import PDFs.
The 4-layer Xero import readiness model
This is the core framework. Most guidance about importing bank statements into Xero stops at Layer 1. That’s like checking whether an envelope fits through a mail slot and assuming the letter inside is correct.
Is the CSV schema valid, the encoding UTF-8, the delimiter correct, the header row in the right position? This is where date locale, signed-amount format, and footer contamination live. A single non-breaking space in an amount cell will kill an import. Xero Central documents these failures explicitly: incorrect date formatting, misaligned columns, invalid CSV structure, excessive field lengths.
Are the dates, amounts, and descriptions right? A file can pass Layer 1 while containing amounts with wrong signs, dates shifted by format misinterpretation, or descriptions truncated during extraction. Five random rows sampled against the source statement will catch most of these. If any amount contains stray currency symbols or thousands separators, stop.
Is the data mapped to the right client, entity, bank account, and currency? Has the Chart of Accounts been confirmed? Are client-specific categorization rules applied, or is every transaction going to hit a generic suspense account during reconciliation?
Have duplicates been checked against prior imports? Do opening and closing balances tie? Has someone reviewed exceptions and low-confidence rows before completing the import?
A file is not truly Xero-ready just because Layer 1 passes.
What should accountants check before importing?
Confirm the correct client and bank account
A technically valid CSV imported into the wrong Xero bank account creates a mess that’s harder to clean up than a failed import. Verify client, entity, bank, account number, and currency before you upload anything.
Confirm the statement period
Count the accounting periods, not just the files. Ten PDFs might cover eleven months. Or nine. Overlapping periods create duplicate risk; missing periods leave gaps that won’t surface until reconciliation. Ask directly: does the converted file cover exactly the period you intended to import?
Confirm every page was processed
This is the failure that opened this article. PDF extraction tools can process a file and produce output without guaranteeing every transaction line was captured. Page counts matter. Continuation pages matter. A cropped or rotated page can silently drop transactions. A statement can still look financially plausible even when an individual page or transaction block is missing.
Verify transaction completeness
Do not rely solely on the final balance. Extraction accuracy alone isn’t enough if page coverage isn’t verified. Check transaction count, page-to-page continuity, date continuity, opening and closing balances, transaction totals, and any unexplained gaps.
Balance validation is not the same as transaction completeness. This is one of the strongest information-gain points in the whole workflow.
Verify opening and closing balances
Opening balance plus transaction activity should equal the closing balance. This is one of the strongest validation checks available.
But here’s what trips people up: a statement can balance and still have missing transactions. If two transactions of equal and opposite value are both dropped, the closing balance still ties. A mismatch can indicate a missing transaction, a duplicated transaction, an incorrect amount, an incorrect sign, an extraction error, or incorrect page processing. Balance verification is necessary. It is not sufficient.
Check transaction dates
Dates that look correct in a spreadsheet can fail in Xero if the format doesn’t match the organisation’s region setting. A UK-based Xero org receiving US-formatted dates will either reject the file or, worse, silently misinterpret them. For example, 03/04/2026 reads as different days depending on regional convention. Xero Central identifies date-format issues as one of the most common manual-import failures. Do not treat third-party claims about exactly which date formats Xero accepts as authoritative unless verified against Xero documentation.
Check debit and credit sign conventions
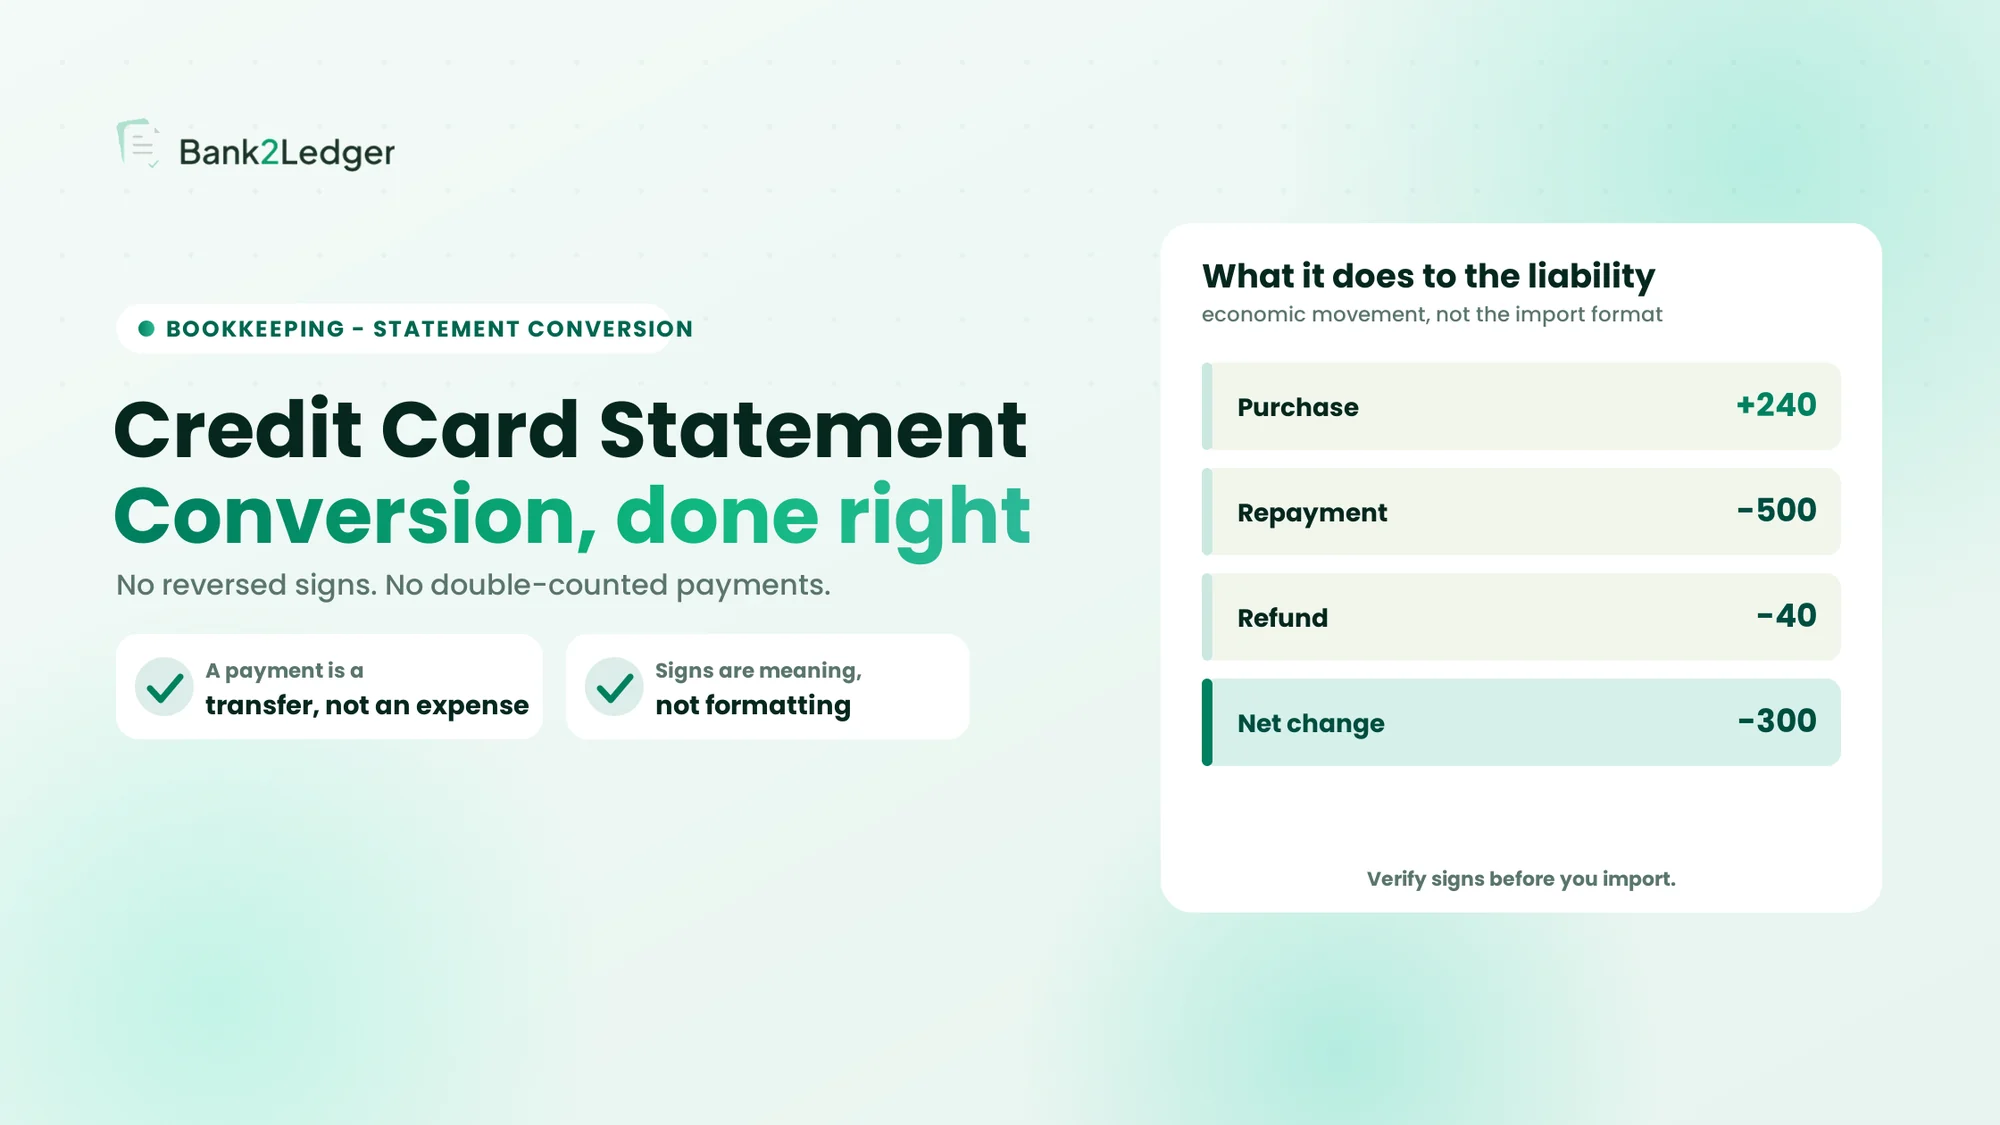
Source statements represent money movement in different ways: separate debit and credit columns, parentheses for withdrawals, signed amounts, or Money-In/Money-Out labels. The converted file needs to use one consistent layout. Mixed structures confuse the import parser.
| Source | Converted |
|---|---|
| Debit 500 | -500 |
| Credit 2,000 | +2,000 |
A sign error can distort income, expenses, the bank balance, and reconciliation. If the import preview shows deposits as withdrawals, stop.
Check amounts and the Xero import structure
Strip currency symbols, thousands separators, and stray characters before import. Xero’s troubleshooting documentation flags amount formatting as a frequent cause of errors. Decimal misplacement is the scariest variant because it doesn’t always trigger a rejection: a $1,500.00 transaction that becomes $150,000 will import just fine.
The destination file generally maps to a small set of fields: date, amount, payee, description, and reference. There is no need to recreate a giant CSV specification here; confirm the fields line up and verify the exact template against current Xero documentation for the client’s region.
Check for duplicate transactions
Xero can identify duplicate transactions that have already been imported, which helps with repeated uploads. It does not help when the duplication exists within the source files themselves, like two overlapping statement periods merged into one CSV. Three scenarios cause duplicates:
Never assume that because Xero flags or handles duplicates, the source file doesn’t need to be reviewed. Control duplicates before import.
Check transaction descriptions and payees
Descriptions drive categorization, transaction matching, and reviewer context. If the conversion process truncated merchant names or stripped reference numbers, downstream work gets harder, especially for firms applying automated categorization rules that depend on description matching. A raw “POS 4837291” is far less useful than “Adobe Creative Cloud”, but be careful: the converter should not invent merchant names when the source doesn’t contain enough information.
Check categorization before import
This is where the article moves from technical conversion to accounting readiness. A converted transaction is not necessarily an accounting-ready transaction.
Extraction asks: “what transaction is present?” Categorization asks: “how should this transaction be treated for this client?”
Check the account and category against the client Chart of Accounts, recurring rules, transfers, owner or director transactions, loan payments, bank fees, and tax-related items. Because the right treatment differs per client, categorization rules need to be client-specific rather than generic.
The gap between converted and Xero-ready is where firms get burned
Bank2Ledger sits in the pre-accounting layer: it extracts transactions from PDFs, verifies balances and completeness, applies client-specific rules, and exports a Xero-ready file, so what reaches Xero has already been checked. See how it works.
Review exceptions before import
Don’t force every transaction through the same path. A good workflow processes the clean transactions, isolates the exceptions, reviews them, then approves and exports. That is far more defensible than blindly importing everything.
| Exception | What to investigate |
|---|---|
| Missing amount | The source statement |
| Unclear transaction | Description and reference |
| Duplicate | Existing Xero data |
| Unusual amount | The original statement |
| Missing category | The client Chart of Accounts |
| Balance mismatch | Transaction completeness |
| Low-confidence extraction | The original PDF |
The ghost errors nobody warns you about
These come from practitioner forums and community threads, not official documentation. They look invisible in Excel but break things in Xero.
| Problem | The weird fix |
|---|---|
| CSV opens fine in Excel but Xero rejects it | Wrong delimiter or encoding. Open in a plain text editor, re-save as UTF-8 CSV |
| Dates look correct but fail import | Date format doesn’t match the Xero org’s region. Reformat every date to match the org locale |
| Amounts import with the wrong sign | Currency symbols, brackets, or mixed debit/credit columns. Strip formatting, convert to one signed amount column |
| Some rows import, others vanish | Blank rows or hidden characters mid-file. Remove all blank rows, paste values into a clean sheet |
| Preview shows a mangled first row | Header row isn’t row 1, or there’s a bank title block above the data. Delete preamble rows |
| File looks right but Xero still errors | Non-breaking spaces or BOM issues. Find-and-replace special characters, re-save as BOM-safe UTF-8 |
Where practitioners disagree
There’s an active debate about whether categorization should happen before or after import into Xero. One camp argues that pre-categorizing transactions upstream, using rules and a Chart of Accounts before the data ever touches Xero, reduces reconciliation time and catches accounting errors earlier. The other prefers importing raw transactions and handling categorization entirely within Xero’s own bank rules and matching engine, keeping the pre-import step purely mechanical.
I land on the pre-categorization side for firms handling volume across multiple clients, because catching a misclassified owner draw before import is cheaper than unwinding it after reconciliation. But this isn’t settled, and the right answer depends on firm size and workflow.
Why a successful Xero import does not prove the data is correct
Import success is a technical outcome, not an accounting-quality assessment. Consider what passes a clean import:
Accepted by Xero is not the same as validated, which is not the same as categorized, which is not the same as reconciled.
Xero import vs bank reconciliation: what is the difference?
Import moves statement lines into Xero. Reconciliation confirms the bank account records align with accounting records. Between those two steps sit categorization and matching, which is where accounting judgment lives. Xero’s documentation directs users to reconcile imported statement lines after import. The sequence matters: convert, import, review, categorize and match, then reconcile.
What if the original bank statement is a PDF?
This is the most common trigger for outsourced bookkeeping teams. The workflow runs: PDF, extraction, validation, categorization, Xero-ready export. Two situations apply.
Do not state “Xero cannot import PDFs” as an absolute. Xero’s PDF support is region and workflow specific, so the honest answer is: check the client’s organization first.
Where Bank2Ledger fits before Xero
Bank2Ledger is positioned as a pre-accounting layer, not a replacement for Xero. It handles the checks above before the data reaches the accounting system:
The verified capabilities are straightforward: PDF upload, transaction extraction, balance verification, client-specific Chart of Accounts and rules, a review queue for exceptions, and CSV export for Xero, built for accounting-firm workflows. It does not promise fully automated bookkeeping, and it does not replace reconciliation.
The bank statement to Xero readiness checklist
A groupable checklist you can run before every import.
Client and account
Statement
Transactions
Accounting
Xero
Common bank statement conversion mistakes before Xero import
A practical workflow for accounting firms
Turned into a repeatable SOP:
Frequently asked questions
Can you convert a bank statement to Xero?
Yes. Conversion turns a source statement (often a PDF) into a structured file Xero can import, such as CSV or OFX. Conversion is a separate step from importing and from reconciling, and a converted file still needs to be validated against the source before you trust it.
What format does Xero use for manual bank statement imports?
Xero Central’s documentation lists CSV, OFX, QFX, QIF, and QuickBooks-compatible files for manual import, and recommends OFX where available because it carries more structured metadata than CSV. Supported options can vary by region and Xero product, so verify against current documentation.
Can Xero import a PDF bank statement?
In certain regions and for supported banks, yes. Check Xero’s current PDF-import documentation for your specific organization before assuming it is available; PDF support is region and workflow specific.
What should I check before importing a bank statement into Xero?
Run the four-layer model: file readiness (format, encoding, headers), data readiness (dates, amounts, signs, descriptions), accounting readiness (correct client, account, Chart of Accounts, rules), and review readiness (duplicates, balances, exceptions reviewed).
Does importing a bank statement into Xero automatically reconcile it?
No. Import and reconciliation are separate steps. Imported statement lines still need to be categorized, matched, and reconciled within Xero.
How do I check whether converted bank statement data is complete?
Check page coverage (every page and continuation page), transaction count and continuity, opening and closing balances, and compare a sample of transactions back to the source statement. A matching balance alone does not prove completeness.
Can duplicate transactions occur when importing bank statements into Xero?
Yes. They happen when the same period is imported twice, when historical data overlaps an existing feed, or when the source file itself contains duplicate rows. Xero can detect previously imported duplicates, but you should also control duplicates at the source.
What should I do if the converted statement doesn’t balance?
Treat it as a validation flag, not an import problem. A mismatch can mean a missing or duplicated transaction, an incorrect amount or sign, or a page that was not processed. Review against the source before importing anything.
Can bank statement conversion also categorize transactions?
Conversion and categorization are separate stages. Conversion extracts what transactions are present; categorization decides how each should be treated for that client, which is why the rules need to be client-specific.
Convert for correctness, not just for a file Xero accepts
The goal of bank statement conversion is not simply to create a file Xero accepts. The goal is to create transaction data that has been checked, understood, and prepared for the client’s accounting workflow.
Converting a bank statement for Xero is the starting line, not the finish. The sequence that actually protects the books is source, convert, validate, categorize, review, import, reconcile. The next problem most firms hit is scaling this validation across dozens of clients without it eating into advisory time.
Turn PDF statements into Xero-ready data you can trust
If your firm processes client bank statements before they reach accounting software, Bank2Ledger sits in that pre-accounting layer: extracting, verifying balances, applying client-specific rules, and exporting Xero-ready files. See how it works.