Every bank account reconciled. Every transaction categorized. Every item on the checklist marked complete. And the books still aren’t right.
I’ve reviewed month-end files where the preparer followed the checklist perfectly and the resulting trial balance still had a suspense account carrying a balance nobody could explain, three reconciling items older than 90 days, and a P&L spike that turned out to be a duplicated deposit from a processor payout mismatch. The checklist said “done.” The books said otherwise.
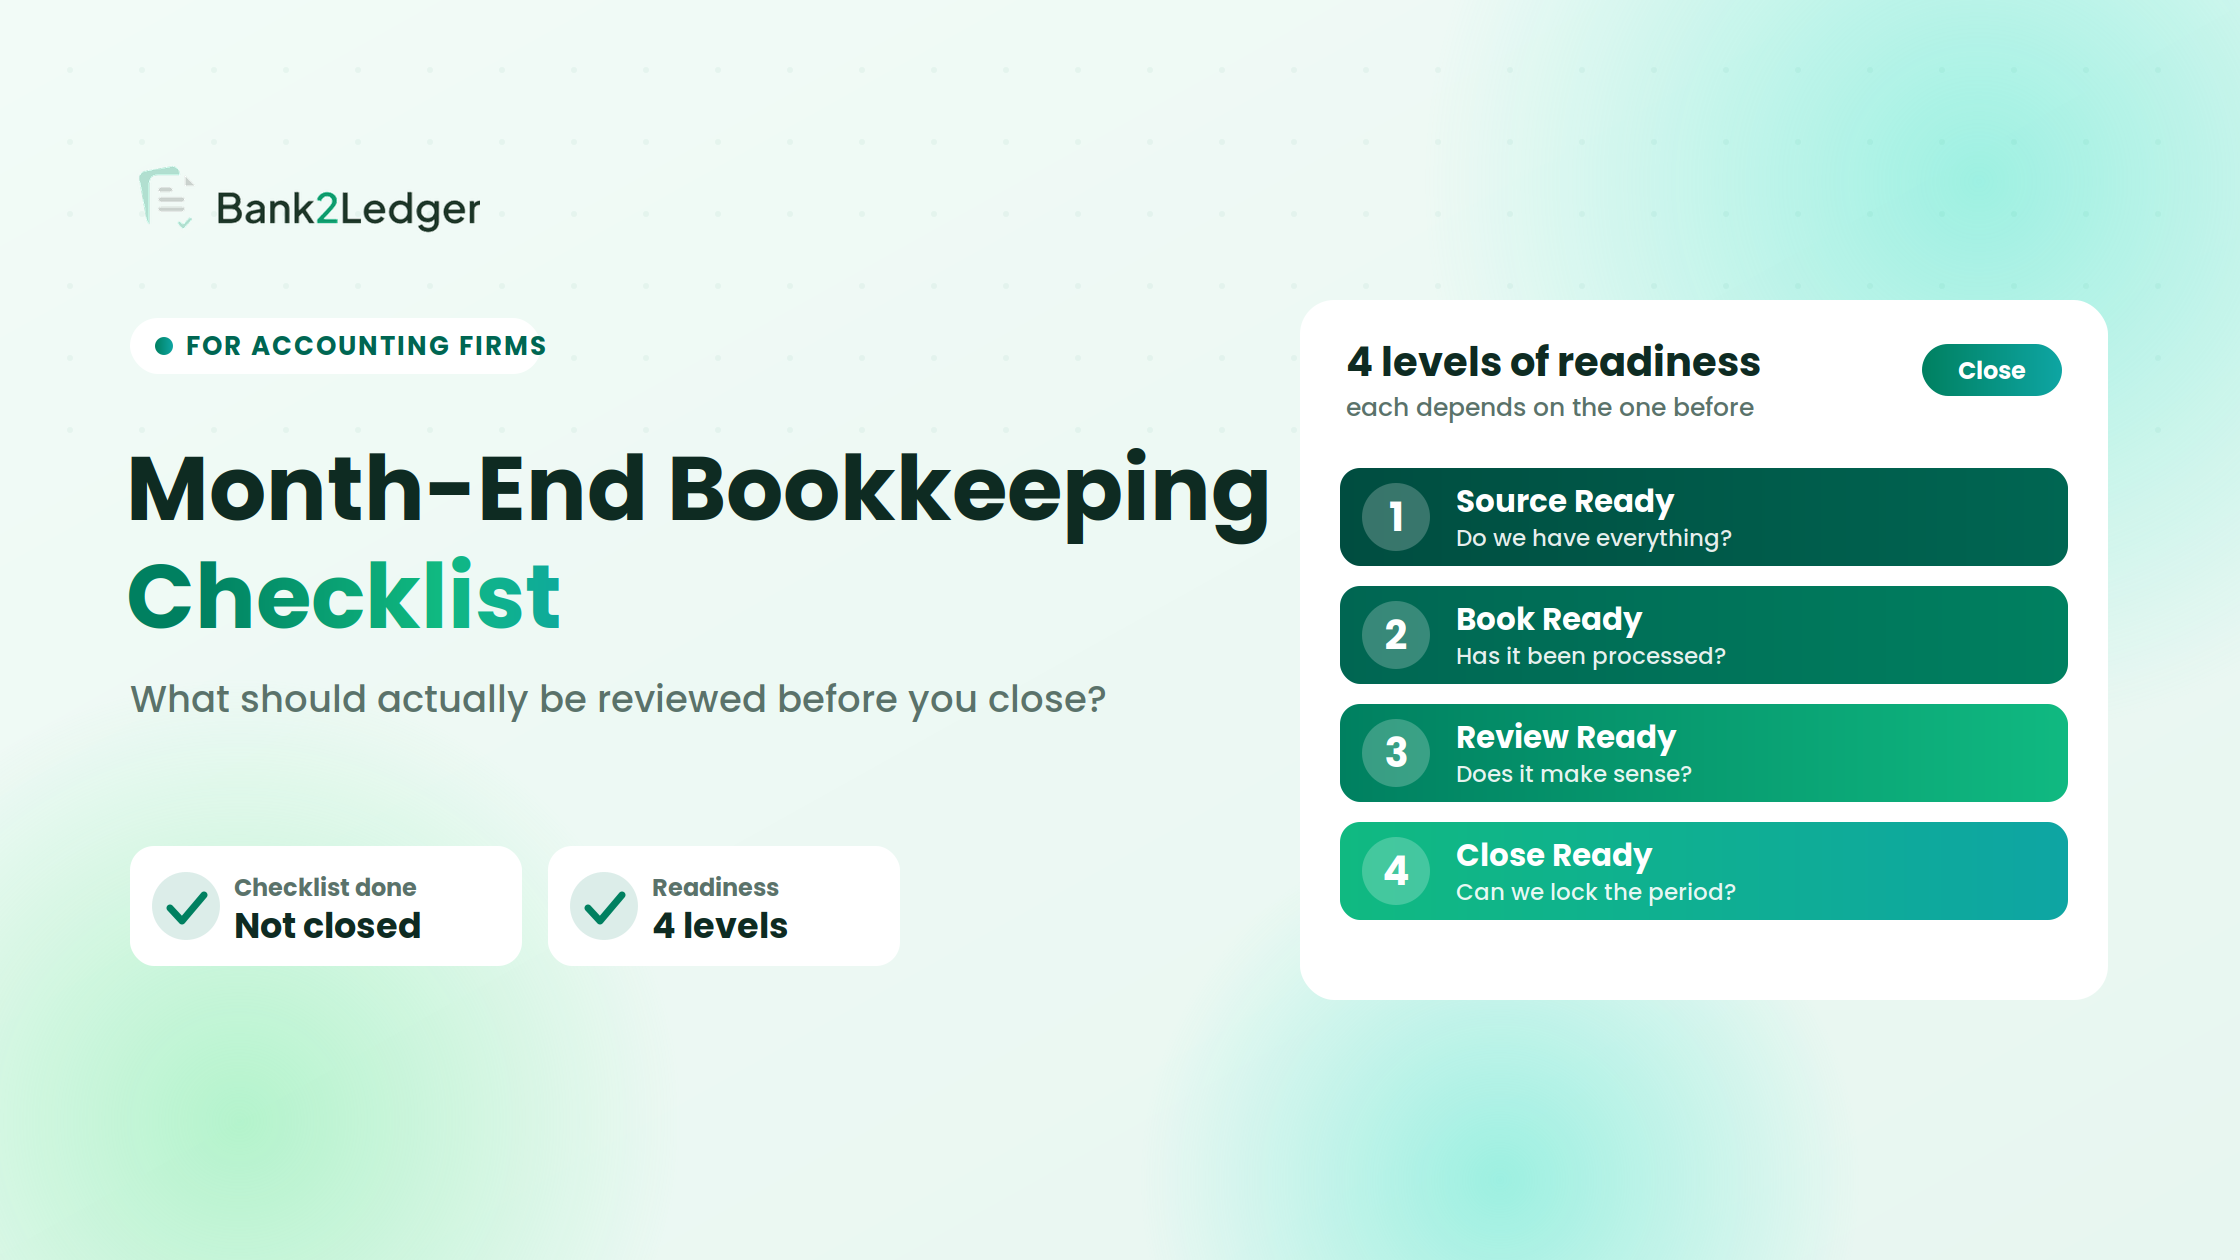
That gap between task completion and close readiness is where most month-end problems live. A completed checklist is evidence that work was performed. It is not evidence that the books can be relied upon. This article uses a four-level readiness framework, Source Ready to Book Ready to Review Ready to Close Ready, to walk through what an accounting firm should actually be reviewing before it considers a client’s period closed.
Completing a month-end checklist is not the same as being ready to close. Evaluate the work across four readiness levels: Source Ready, Book Ready, Review Ready, and Close Ready. A task completed is not the same as an account reviewed, which is not the same as a period closed.
- Reconciled means the record matches the source. Reviewed means the result makes sense. They are not the same step.
- Every open item needs an owner, a status, and a next action, not just an unchecked box.
- Run a 7-question readiness test before calling a period closed.
- Much of the work happens before the accounting software, in how clean the source statement data is.
What is a month-end bookkeeping close?
Define month-end bookkeeping close
A month-end bookkeeping close is the process of finishing transaction processing, reconciliations, adjustments, and review so the accounting records are ready for reporting and the next period. In practice that generally involves completing transaction processing, reconciling the relevant accounts, reviewing exceptions, posting required adjustments, reviewing the resulting records, and finalizing the period according to the firm’s defined process.
The definition is stable. What varies enormously is the scope. One client might need bank and credit card reconciliations only. Another requires AR/AP subledger tie-outs, payroll liability rollforwards, prepaid amortization, and deferred revenue postings. The close procedure has to reflect the engagement, not a generic template.
Why the close is more than a checklist
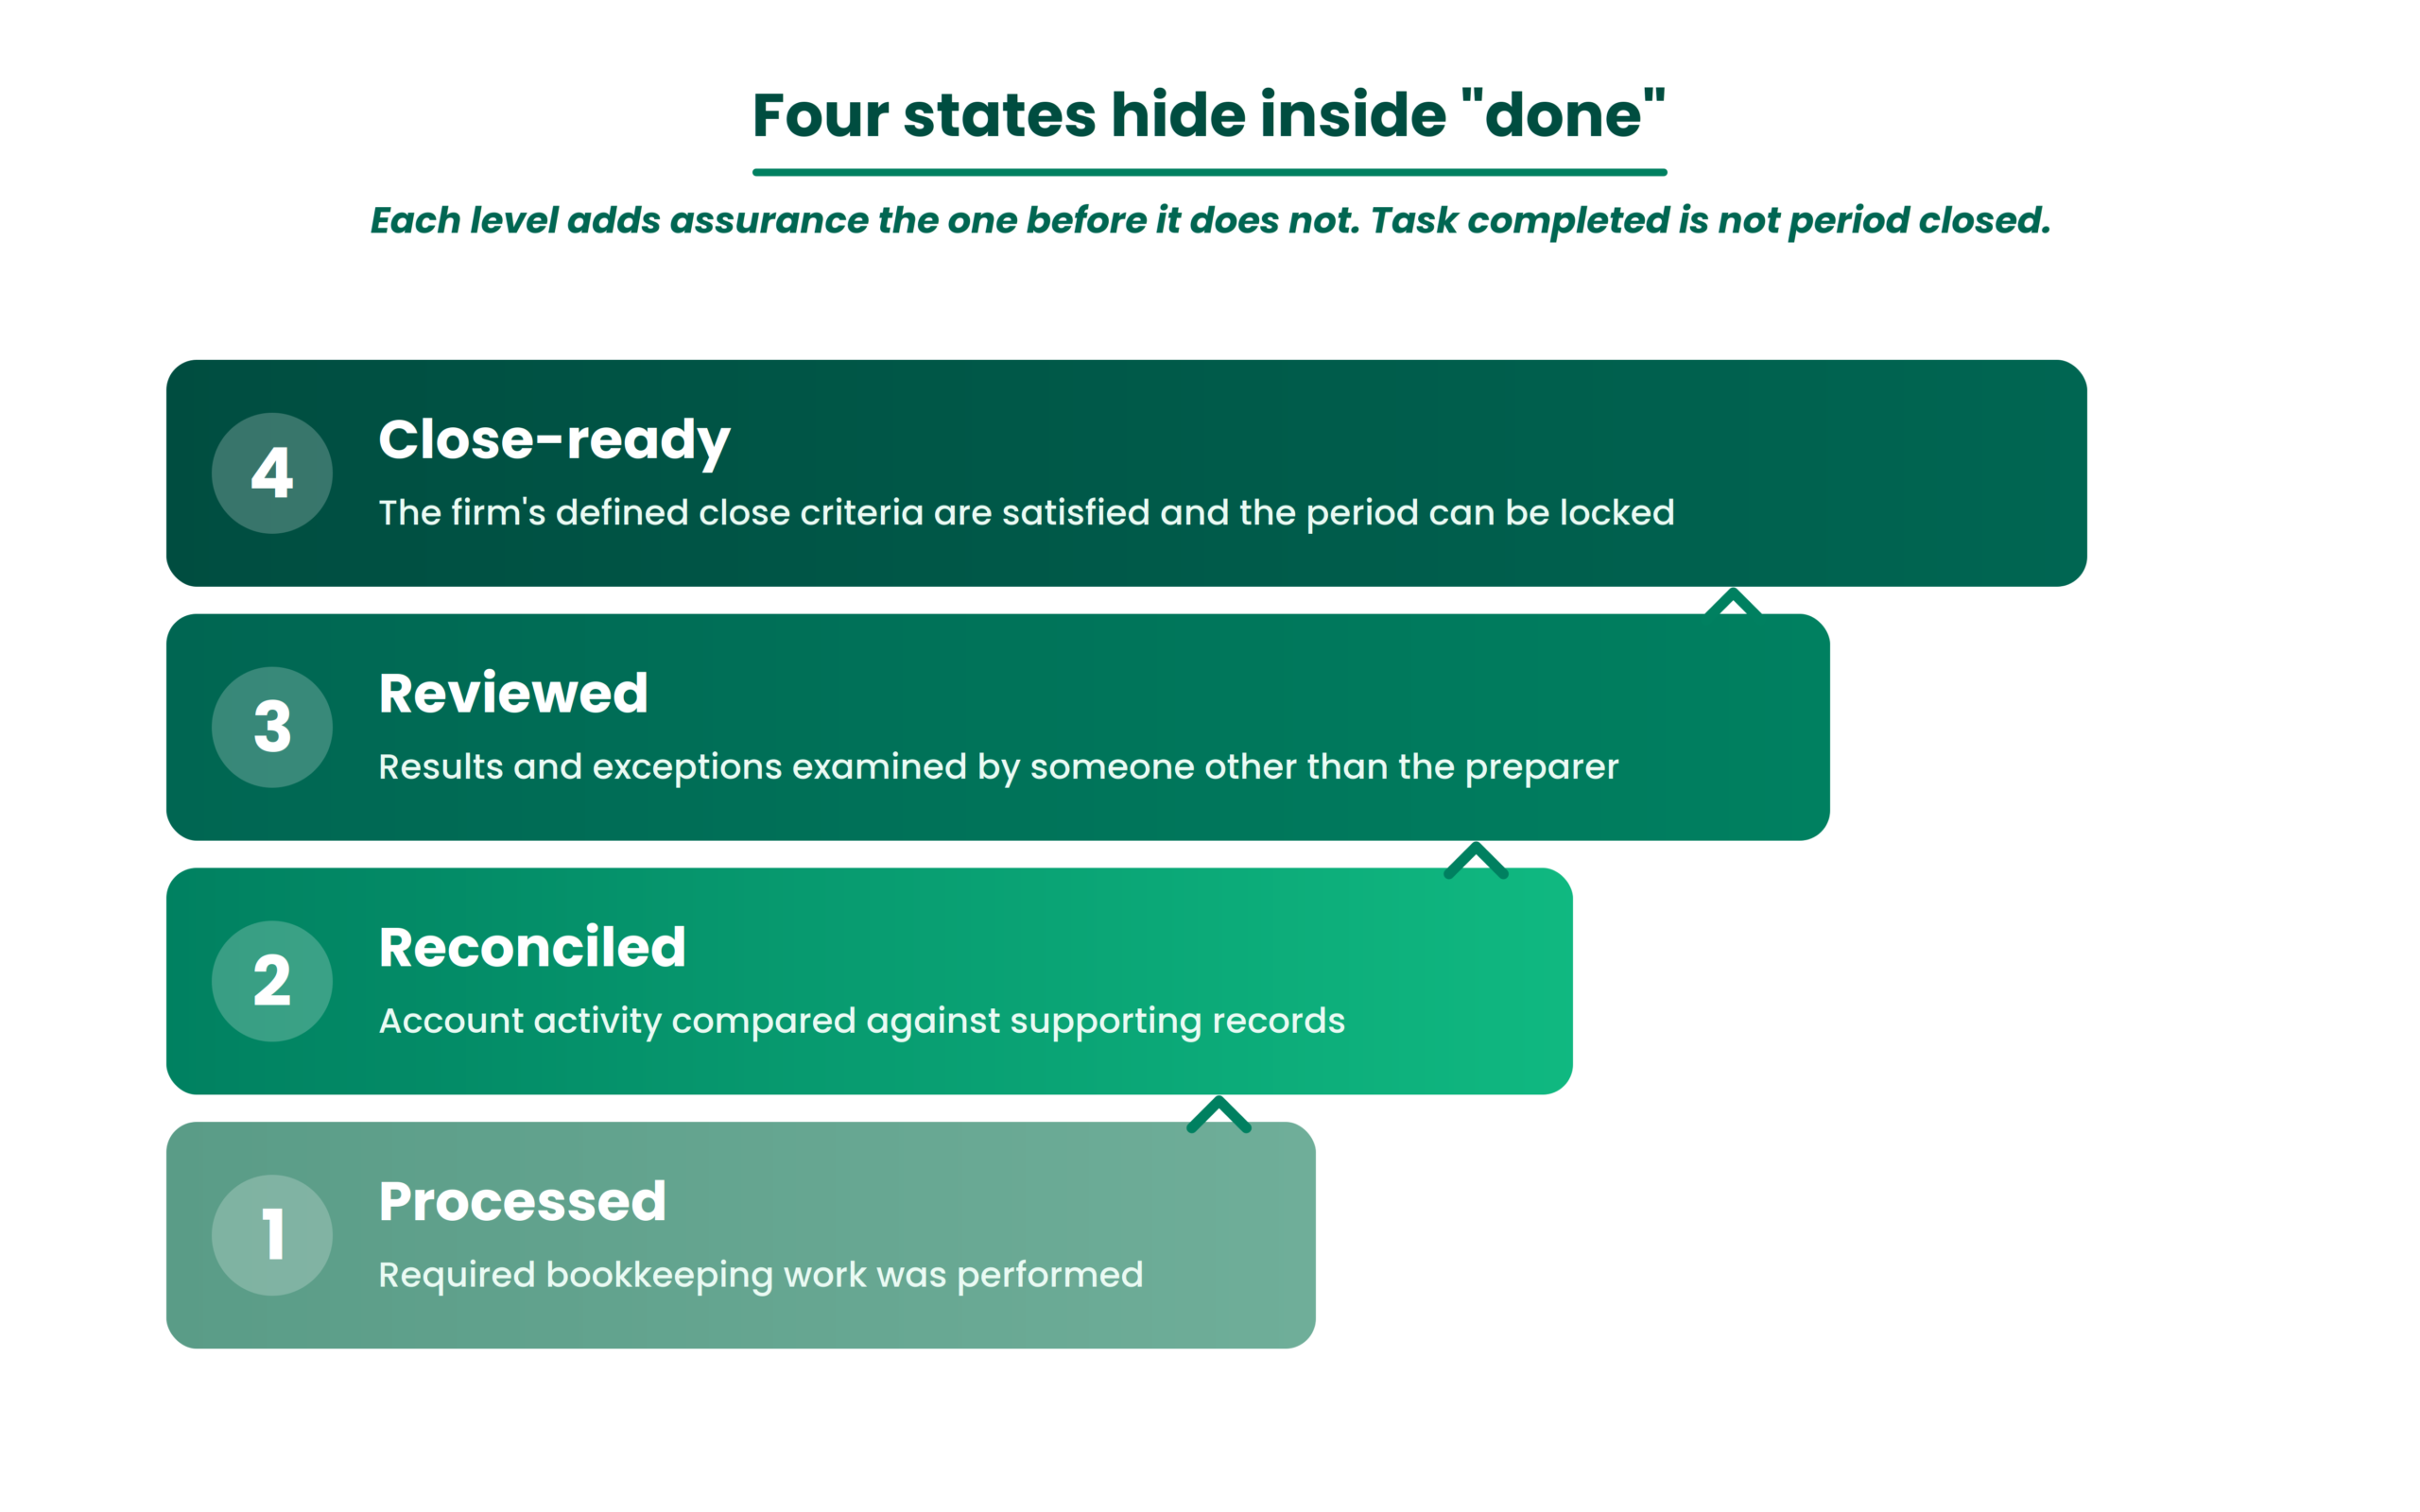
The word “closed” gets used loosely, and that looseness causes problems. Task completed is not the same as account reviewed, which is not the same as period closed. Four distinct states tend to get collapsed into one:
| Status | Meaning |
|---|---|
| Processed | Required bookkeeping work was performed |
| Reconciled | Account activity was compared against supporting records |
| Reviewed | Results and exceptions were examined by someone other than the preparer |
| Close-ready | The firm’s defined close criteria have been satisfied and the period can be locked |
A bookkeeper saying “the month is done” might mean any of those four things. Without a shared definition, the reviewer does not know what “done” actually claims. Some of this readiness is set upstream, before the accounting software ever sees the data, which is the pre-accounting step between bank statements and the general ledger.
The 4 levels of month-end readiness
Before calling a month complete, an accounting firm can evaluate the work across four levels of readiness. Each level depends on the one before it. Skip a level and you are building on assumptions.
1. Source Ready
Do we have the information required to perform the month’s bookkeeping? That means bank statements, credit-card statements, loan information, payment processor records, payroll information where applicable, invoices and bills where applicable, client explanations, and any other engagement-specific source records.
What matters is that the firm knows the difference between information that is not needed, information that is pending, information that is blocking the close, and information that has been resolved. For a deeper look at managing statement collection specifically, the bank statement intake checklist for accounting firms covers that workflow.
Key question
Do we have everything required to start and complete the month’s work?
2. Book Ready
Has the required bookkeeping work actually been processed? Transactions recorded, transactions categorized, transfers handled, recurring items processed, adjustments posted where applicable, relevant accounts reconciled, and known exceptions identified.
This is where most generic checklists start and stop. But a transaction can be present without being correctly categorized. It can be categorized without being reconciled. It can be reconciled without being reviewed. Those are separate states, and each one adds a layer of assurance the previous one does not.
Key question
Have the required books been processed?
3. Review Ready
Are the resulting books ready for someone to review meaningfully? Review ready means someone can examine unexplained differences, unusual transactions, large balance changes, uncategorized items, old reconciling items, suspense and clearing balances, and unresolved client questions, without first having to discover basic missing information.
Review is not checking whether the preparer followed the checklist. It is checking whether the resulting books make sense for this client, this month, given what you know about the business.
Key question
Can a reviewer evaluate the books without first having to discover basic missing information?
4. Close Ready
Has the firm satisfied its defined criteria for finalizing the period? Close ready means required processing is complete, relevant reconciliations are complete, significant exceptions are addressed, required adjustments are posted, review is complete, open items are documented with owners, and reports are ready.
Some legitimate open items may remain depending on the engagement. The important thing is that they are identified, understood, and handled according to the firm’s process.
Key question
Can the firm reasonably consider the period complete under its own close process?
Month-end bookkeeping checklist
This is the practical core. Work it as review areas, not one enormous bullet list. Each subsection has a purpose and, where useful, a short checklist.
1. Confirm the month and scope
Start by confirming the client or entity, the accounting period, the bookkeeping cutoff, the services included in the engagement, the accounts included, the client’s responsibilities, and the firm’s responsibilities. The firm needs a defined boundary before it can determine whether the month’s work is complete.
2. Confirm all required source data has arrived
Check for bank statements, credit-card statements, loan statements, payment processor reports, payroll information, bills and invoices, and any other relevant source documents. Receiving a document is not enough. The firm should know whether it received all documents required for the month, that each covers the full period, and whether each has been reviewed.
| Source | Received? | Period complete? | Reviewed? |
|---|---|---|---|
| Bank statements | |||
| Credit-card statements | |||
| Loan statements | |||
| Payment processor reports | |||
| Payroll information | |||
| Bills and invoices |
A small register like this turns “we got the statements” into “we confirmed coverage.”
3. Review bank and cash accounts
Check that all relevant accounts were processed, with the correct statement period, opening balance, closing balance, transaction coverage, missing transactions, duplicate transactions, transfers, reconciliation status, and any outstanding differences.
A bank account should not be considered finished merely because someone clicked “reconcile.” Differences and unusual items may still require investigation.
Two failure modes are worth reading about before your next close: whether a bank statement can balance and still have missing transactions, and bank statement reconciliation after PDF conversion, where extraction gaps surface as reconciling differences.
4. Review credit cards and other financial accounts
Where applicable, cover credit cards, loans, merchant accounts, payment processors, clearing accounts, and other financial accounts within scope. For each, check statement completeness, reconciliation, unusual balances, unresolved items, and correct classification. Not every client has every account, so apply this only where the account is in scope.
5. Review transaction categorization
Check uncategorized transactions, unusual transactions, inconsistent categorization, transfers, recurring transactions, large transactions, and client-specific treatments. The real question is whether the categorization makes sense for this client, not merely whether every transaction has a category.
Key question
Does the categorization make sense for this client, not just: does every transaction have a category?
This is why bank transaction categorization rules need to be client-specific, and why it helps to automate bank transaction categorization with rules and a chart of accounts rather than recoding the same vendors by hand each month.
6. Review reconciliations
Treat reconciliation as a control, not a checkbox. Check the bank reconciliation, credit-card reconciliation, relevant balance-sheet accounts, clearing accounts, old reconciling items, and unexplained differences.
Reconciled does not automatically mean reviewed. A reconciliation confirms the record matches the source. Review confirms the result makes sense and that exceptions have been addressed.
7. Review suspense and clearing accounts
Cover suspense accounts, payment processor clearing, payroll clearing, transfer accounts, and temporary holding accounts. For each, answer: what is the balance, why does it exist, is it expected, is there supporting information, and does it require action? A suspense or clearing account does not always have to be zero, but any balance should be explainable.
8. Review accounts receivable and accounts payable
Only where these are included in scope. For accounts receivable, review unusual balances, significant changes, old outstanding items, missing information, and credits. For accounts payable, review unusual balances, outstanding bills, credits, missing bills, and significant changes. Keep this focused on month-end review rather than a full AR/AP tutorial.
9. Review adjustments and recurring entries
Depending on the engagement, this may include accruals, prepayments, depreciation, loan-related entries, payroll entries, recurring journals, and other engagement-specific adjustments. Not every client requires all of these, so post only what the engagement calls for.
What should a reviewer look for at month-end?
Review moves beyond the checklist. Five questions frame what a reviewer actually evaluates.
Completeness
Did we receive and process everything we expected for the period?
Accuracy
Do the records agree with the relevant supporting information?
Consistency
Does the current month’s accounting treatment follow the client’s established approach?
Exceptions
What remains unresolved, and is each open item tracked?
Reasonableness
Do significant balances or movements make sense given what you know about the business?
| Review area | Question |
|---|---|
| Completeness | Did we process everything required? |
| Accuracy | Do records agree with supporting data? |
| Consistency | Does treatment follow the client’s established approach? |
| Exceptions | What remains unresolved? |
| Reasonableness | Do significant changes make sense? |
If a reviewer approves a close but cannot articulate what they checked and why, the review is ceremonial. Documentation is part of the review, not an afterthought.
Reconciliation vs. review: what’s the difference?
These two get conflated constantly, and the confusion is expensive.
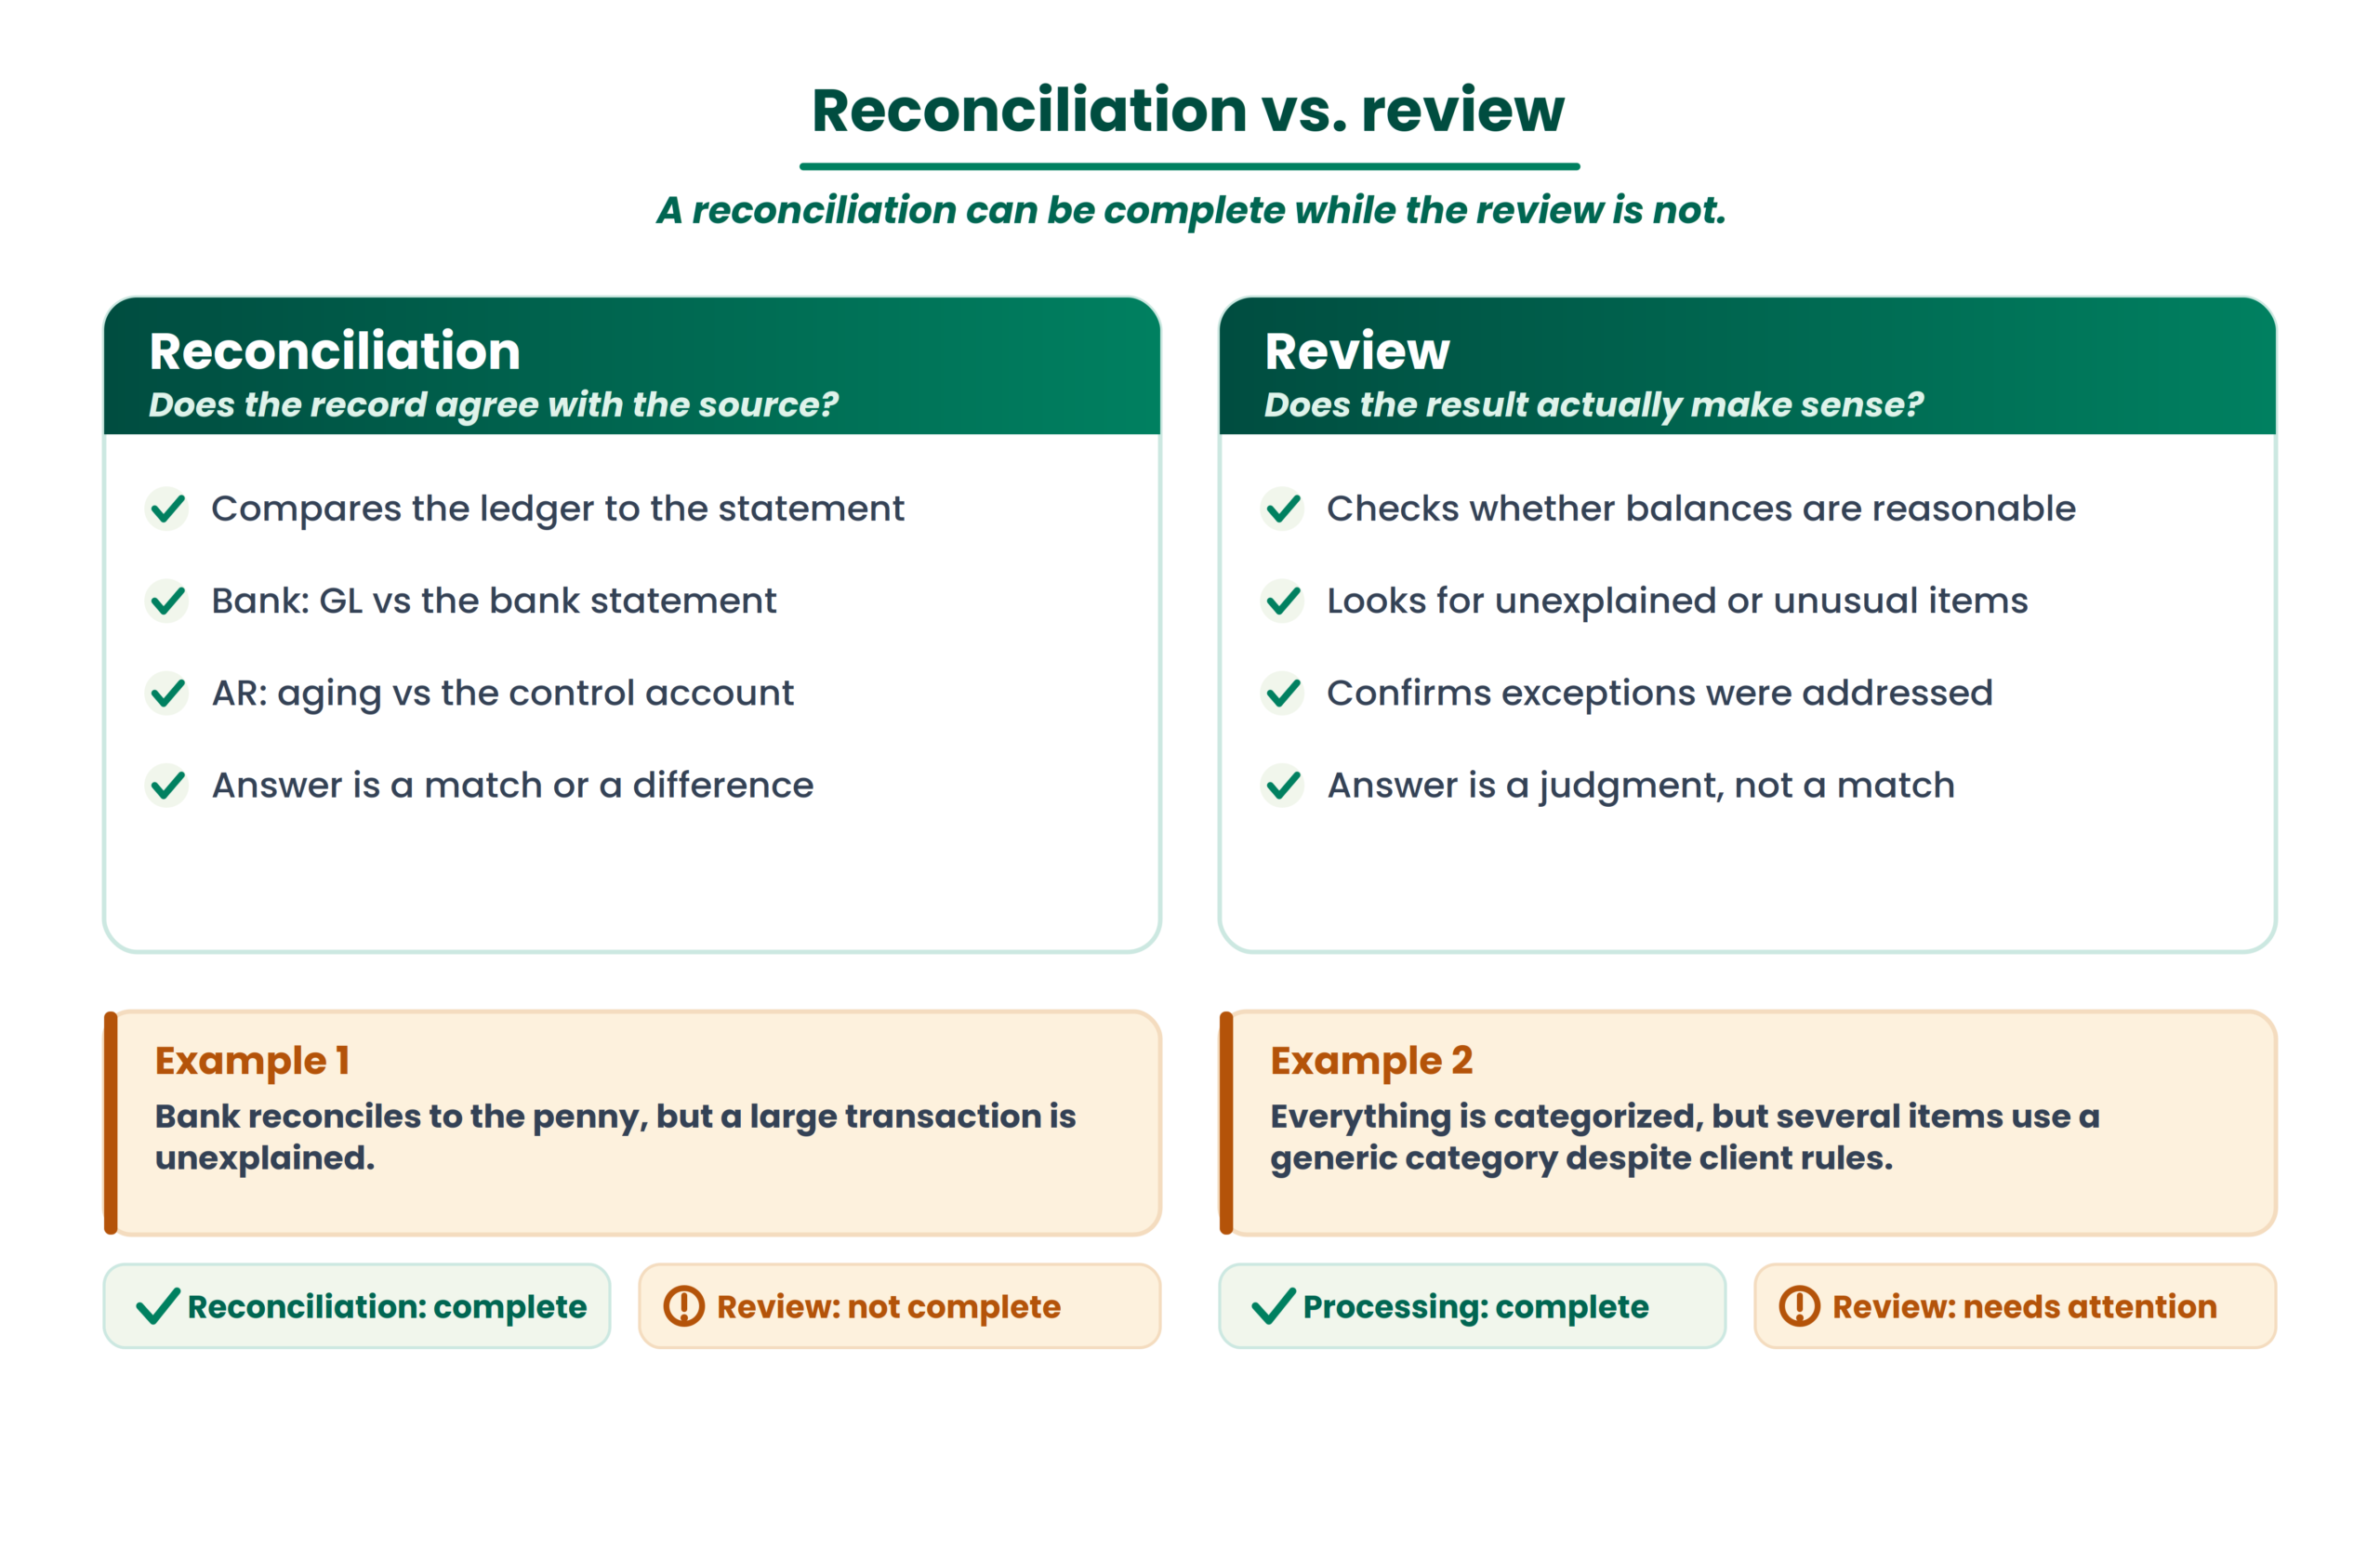
What reconciliation answers
Does the accounting record agree with the relevant external or supporting record? A bank reconciliation compares the general ledger to the statement. An AR reconciliation compares the aging to the control account.
What review answers
Does the resulting accounting information make sense, and have significant exceptions been addressed? A reconciliation can be complete while the review is not.
Example 1. A bank account reconciles to the penny, but there is an unusual large transaction that has not been explained. Reconciliation: complete. Review: not necessarily complete.
Example 2. All transactions are categorized, but several were assigned a generic category despite client-specific rules. Processing: complete. Review: requires further attention.
What should happen when something is still open?
Generic checklists treat open items as binary: done or not done. In practice, every open item belongs in an exception register with an owner, a status, and a next action.
What is an exception?
An exception is an item that prevents the firm from confidently treating part of the month’s work as complete, or that requires additional review. Common examples: a missing statement, an unknown transaction, a reconciliation difference, a duplicate, an unusual balance, missing documentation, or an item needing client clarification.
Give every exception an owner
An open item without an owner floats. It gets carried forward month after month as something to check later. A simple register keeps each one moving:
| Exception | Impact | Owner | Status | Next action |
|---|---|---|---|---|
| Missing statement | Blocking | Client | Pending | Request statement |
| Unknown transaction | Review | Bookkeeper | Investigating | Compare to source |
| Reconciling difference | Review | Bookkeeper | Open | Isolate unmatched item |
| Unusual expense | Review | Reviewer | Open | Confirm treatment with client |
Don’t hide exceptions to complete the checklist
An unresolved issue should not disappear simply because the month-end checklist has a checkbox for the account. It helps to distinguish four states for every exception:
When is a month actually ready to close?
The 7-question close readiness test
Before you call a period closed, answer these:
A “no” answer does not always mean the entire month must remain open. It means the firm needs to understand whether the item is blocking, non-blocking, or requires documented follow-up. If any answer is no, the period may be processed. It is not close ready.
Common month-end bookkeeping mistakes
1. Treating the checklist as proof of accuracy
A completed task shows that work was performed, not that the result is correct. A checklist is a record of activity, not evidence that the books can be relied upon.
2. Closing before all required source data arrives
Closing on partial source data guarantees rework. A missing statement or an incomplete processor report surfaces later as an unexplained difference, usually after reports have gone out.
3. Treating reconciliation as the final review
A reconciliation confirms the record matches the source. It does not confirm that old reconciling items were investigated, that categorization is correct, or that balances make sense in context.
4. Ignoring old reconciling items
Recurring unresolved items obscure the current month’s work. The same aged difference cycling through every close hides new problems and erodes trust in the books.
5. Leaving exceptions without owners
“Pending” without a named owner is not a workflow. An exception that nobody owns is carried forward indefinitely instead of resolved.
6. Using the same close process for every client
A standardized core process is good; applying identical close requirements to every client is not. The engagement defines which accounts, adjustments, and reviews actually apply.
7. Automating processing without an exception workflow
Automation speeds up processing, but automation without a review and exception process is just faster errors. The exceptions still need a human and an owner.
A practical month-end close workflow for accounting firms
Each step depends on the one before it. You cannot meaningfully review what has not been processed, and you cannot confidently close what has not been reviewed.
Where Bank2Ledger fits into the month-end workflow
Some month-end problems begin before the accounting software. If source bank statements are incomplete, poorly structured, or inconsistently categorized, the downstream bookkeeping and review process inherits those problems. If transactions are miscategorized during import, the categorization review has to catch them; if that review misses them, the reconciliation might still pass because totals match; and then the reviewer has to catch a coding error buried inside a clean-looking rec.
Bank2Ledger sits in the pre-accounting stage. It helps prepare bank-statement transaction data before it moves into the accounting workflow: PDF statement upload, transaction extraction, balance verification, client-specific Chart of Accounts and rules, a review queue for exceptions, and CSV export for Xero and other supported accounting destinations. It does not perform the entire month-end close; it cleans up the source layer the close depends on.
For the reasoning behind this, why bank statement extraction accuracy is not enough for accounting firms explains why extraction alone does not make data close ready, and what pre-accounting is frames where this step sits relative to the general ledger.
Start the close with clean source data
If your month-end bottleneck starts with statement processing, Bank2Ledger handles extraction, balance verification, and client-specific categorization before data reaches your accounting software. See how the upload-to-export workflow works.
Month-end bookkeeping close checklist
A scannable version, organized by workflow stage rather than random task order.
Source readiness
Processing
Reconciliation
Review
Close
Frequently asked questions
What is a month-end bookkeeping checklist?
A month-end bookkeeping checklist is a structured review a firm works through before closing a client’s period. A useful one covers four readiness levels: source readiness (all required documents received and confirmed), book readiness (transactions processed, categorized, and reconciled), review readiness (exceptions investigated and unusual items explained), and close readiness (reviewer sign-off complete, period locked, reports produced).
What should be reviewed before closing the books?
Source data completeness, transaction processing and categorization, reconciliations of bank and other accounts, suspense and clearing balances, significant or unusual movements, and any open exceptions. The review confirms not just that work was done, but that the resulting books make sense for this client and this month.
Does completing a bank reconciliation mean the books are ready to close?
Not necessarily. A reconciliation confirms the general ledger matches the bank statement. It does not confirm that old reconciling items were investigated, that categorization is correct, or that the resulting balances make sense in context. Reconciliation is one control; it is not the entire review.
What should a bookkeeper check at month-end?
Scope and cutoff, source data arrival, bank and cash accounts, credit cards and other financial accounts where applicable, transaction categorization, reconciliations, suspense and clearing accounts, AR and AP where in scope, and any required adjustments and recurring entries.
Should every bookkeeping client use the same month-end checklist?
A firm should run a standardized core workflow, but the specific accounts, adjustments, and reviews depend on the engagement. One client may need only bank and credit-card reconciliations; another needs AR/AP tie-outs, payroll rollforwards, and deferred revenue. Standardize the process, not the identical task list for every client.
What should happen to unresolved bookkeeping issues?
Every open item should be logged with an account, an impact assessment, a named owner, a current status, and a defined next action. Carrying unresolved items forward without ownership is how small issues become recurring problems that erode trust in the books over months.
Can bank statement processing be automated during month-end?
Parts of it, yes. Extraction, balance verification, and rule-based categorization can be automated with high accuracy, and the pre-accounting step between bank statements and the general ledger is where automation adds the most value. Exception review and judgment calls on unusual transactions still require a human. Automation without a review process is just faster errors.
When is a bookkeeping period considered closed?
When the firm’s own defined close criteria are satisfied: source information received, relevant accounts processed and reconciled, significant differences understood, exceptions documented with owners, required review completed and signed off, and reports produced. There is no single universal standard; the firm defines what closed means for each engagement.
Make the books understood, not just checked
The close is a sequence, and each step depends on the one before it:
The goal of month-end bookkeeping is not to make every checkbox green. It is to make the accounting records sufficiently complete, reviewed, and understood for the firm’s defined reporting purpose. A completed checklist proves work happened. The readiness framework proves the books can be relied upon.
Make the pre-accounting stage more consistent
For firms processing large volumes of bank statements, improving the pre-accounting stage makes the downstream bookkeeping and review more consistent. Bank2Ledger is designed to sit between source statements and the accounting system.